
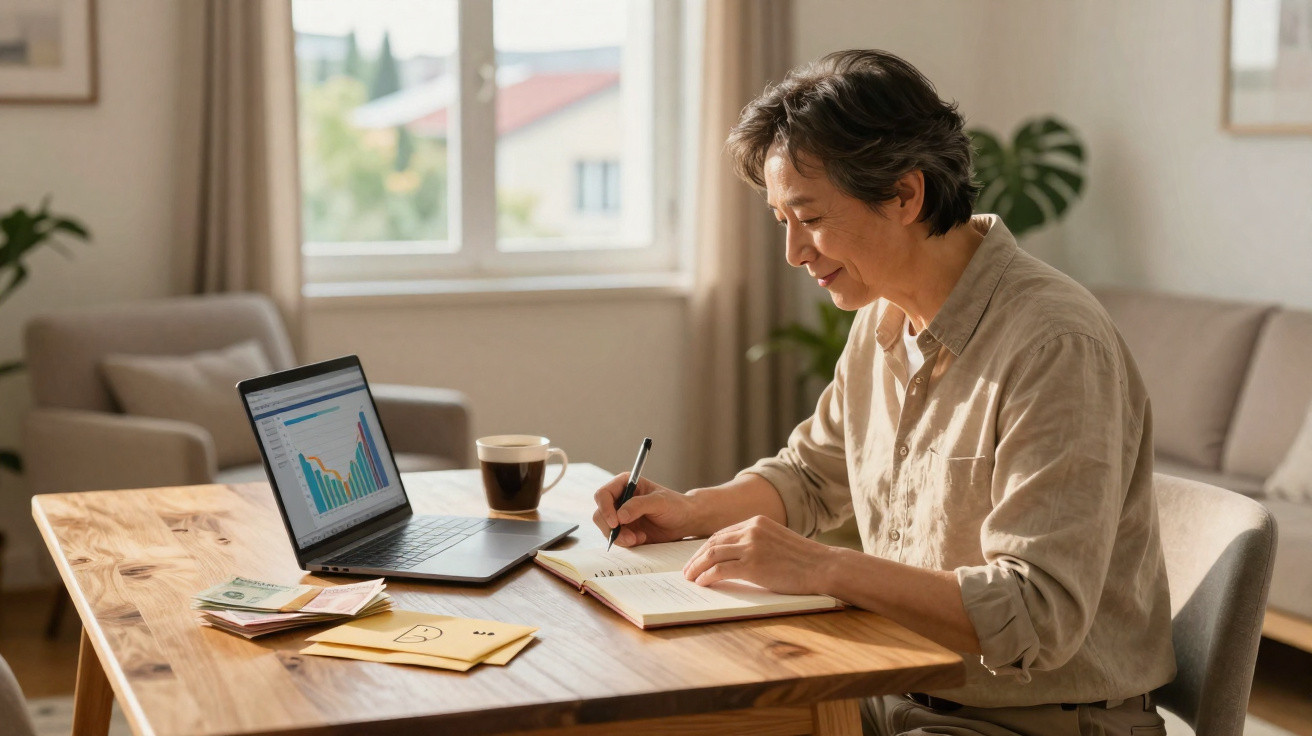
The evening light catches the pile of envelopes on the kitchen table, making them seem oddly menacing. A bank statement. An energy bill. A letter from the pension provider, full of figures that do not quite resemble the future you pictured at 30. As you stir your tea and watch the steam curl upwards, the familiar thought returns: “Is this really enough for one person to live on?”
The fridge buzzes, your neighbour’s television can be heard through the wall, and the calculator app remains open on your phone like an accusation. You enter rent, food shopping, health insurance, a little spending for socialising and a small category labelled “pleasure” - then delete it and enter a lower amount.
Somewhere between housing and groceries, an unspoken question lingers.
How much does a single person truly need to retire without anxiety?
What is the “ideal” pension for living alone?
Attend almost any retirement seminar and you are likely to hear the same broad advice: “You’ll need around 70–80% of your final salary.” It sounds comforting, until you return home, sit at your own table and realise that this percentage must cover actual rent alongside increasingly expensive food shopping.
For a person living alone, that rule of thumb can seem far too vague. There is no partner to split the bills with and no second income to cushion financial shocks. Your pension is not simply a figure; it is your room for error. This is why an increasing number of financial planners discuss firm monthly sums rather than reassuring percentages.
Viewed this way, the calculation changes considerably.
Take a practical example. Claire is 65, lives alone in a medium-sized city, rents a modest one-bedroom flat and does not lead an extravagant lifestyle. Her monthly costs might look like this: 900 for rent and housing bills, 300 for food, 150 for health-related costs, 100 for transport, 150 for basic leisure and clothing, and another 100 reserved for unexpected expenses.
That already comes to roughly 1,700 each month, with no luxuries included. There are no major holidays, expensive restaurants or help towards a grandchild’s car deposit. It is simply a modest, steady life. Claire’s state pension? 1,250 a month.
You can sense the shortfall before it even appears in a spreadsheet.
Putting figures around it, many financial planners now privately acknowledge that a single city renter’s “ideal comfort zone” frequently begins at around 1,800–2,200 net per month. Below 1,500, every penny must be monitored. Above 2,200, there is room to breathe, deal with a few surprises, go out and travel occasionally.
Naturally, the appropriate amount varies by location. A homeowner in a rural area with no mortgage may manage on around 1,400–1,600. For a renter in a major city, the threshold is more likely to be 2,200–2,500. The true ideal is not a magic number; it is the point at which your shoulders finally relax when you think about money.
That is the figure worth working towards over the decades.
How to work out your own “solo retirement number”
The most useful approach is straightforward, though slightly uncomfortable. Use a piece of paper - or a spreadsheet, if you prefer - and map out your future life as though you were already living it. Consider where you will live, how regularly you will eat out and whether you will own a car or rely on public transport. Then assign a monthly cost to every item.
Begin with housing: rent, or council tax and property charges. Next, add food, transport, health, insurance, phone and internet, leisure, gifts, a modest travel allowance and a “life happens” fund. Complete the exercise first using your current lifestyle, then repeat it with a slightly more modest version and a slightly more generous one.
Those three totals form your personal retirement range: survival, comfortable and ideal.
Many people avoid this task because they fear what they might find. We have all experienced that moment when opening the banking app feels easier to put off. Yet this is precisely where living alone can give you power. You may be able to make changes more flexibly than a couple with children and shared commitments.
Suppose your ideal target is 2,000 per month. Look at what your expected state pension will provide; even a basic calculator is sufficient. If it indicates 1,300, the position becomes clear: you need to find 700. That might come from savings, part-time work during early retirement, rental income or downsizing.
Figures stop feeling theoretical once they are attached to your future Saturday mornings.
There is also a psychological pitfall. Many single people underestimate their spending because they assume that “one person” means “half the cost”. In reality, it rarely works that way. Rent does not halve. Heating changes very little. Internet, subscriptions and many fixed bills remain exactly the same. Living alone means carrying 100% of them yourself.
This is why it helps to think in categories. Housing and regular bills are non-negotiable. Food and leisure offer more flexibility. Health is an unpredictable cost that often increases with age. Your ideal pension is the sum that pays for the non-negotiables while leaving room for dignity and enjoyment.
Anything below that threshold can feel like a permanent compromise, even when you do not voice it.
Strategies for reaching an ideal solo pension
Once you know your target, the next question is how to move closer to it without completely overturning your life. One particularly effective step is to practise your retirement budget before you retire. For three months, live as if you received only that future income and save the difference.
If your goal is 1,900 and you currently earn 2,500, try living on 1,900 now. Put the remainder into a separate account or pension plan. This works as both a test and a training exercise. It shows you what feels difficult, what can easily be cut and what you are unwilling to sacrifice.
That kind of “rehearsal” is more valuable than any theoretical forecast in a glossy brochure.
There is also the question of lifestyle, which can be slightly uncomfortable to address. Many people imagine retirement as a lengthy holiday, but everyday life usually resembles life now: food shopping, laundry and scrolling on the sofa. Let us be honest: no one truly checks every small budget category every day.
The key is to settle the biggest decisions early: where you will live, the type of home you want and whether you intend to have a car. Those three choices can alter your ideal pension target by several hundred per month. Moving to a flat one suburb further out, choosing a smaller car or relocating to a less expensive town can sometimes do more for retirement than ten years of unenthusiastic saving.
Adapting your dream to fit the figures is not failure. It is simply how you make that dream achievable.
“I used to think an ideal pension meant a big number,” says Marc, 68, who lives alone in a coastal town. “Now I see it’s not just about how much comes in, it’s about how light my fixed costs are. Once my rent went down, every euro felt bigger.”
- Establish your genuine minimum, comfortable and ideal monthly budgets well before retirement.
- Try a three-month “retirement rehearsal” to test your future lifestyle and identify pressure points.
- Concentrate on the highest-impact factors: housing costs, car ownership and clearing debt.
- Draw on several income sources: state pension, savings, a small side activity and perhaps a room to let.
- Safeguard your future self with an emergency fund specifically for health costs and home repairs.
When “enough” means more than a bank balance
Eventually, the discussion of an “ideal pension” becomes more than a financial matter; it becomes something personal. What would a good day look like when you are 70 and living alone? Would it involve coffee on the balcony, a train journey to visit friends, a yoga class or a hobby you never previously had time for? Those images matter as much as any calculation.
For one person, an ideal solo retirement could mean 1,600 per month in a small town, with a vegetable garden, a second-hand car and time for reading. For someone else, it may mean 2,300 in a lively city, with a cinema pass, meals out and weekend breaks. Money provides the frame, but what fills it is intensely personal.
Once you have faced the uncomfortable figures, something interesting often follows: anxiety becomes decision-making. You may choose to work for an additional two years, not because you are forced to, but because you can see exactly what those extra contributions will provide later: greater freedom, more security and fewer sleepless nights.
Or you might make the opposite choice: accept a somewhat lower pension while moving somewhere cheaper, nearer to nature or friends. Suddenly, “ideal” no longer means “perfect”. It means being aligned with who you are and the life you genuinely want when there is no manager, no timetable and no second pay packet in the household.
That is the quiet revolution concealed in those dry pension letters on the kitchen table.
| Key point | Detail | Value for the reader |
|---|---|---|
| Set your own target | Calculate three budgets: minimum, comfortable and ideal for living alone | Turns vague anxiety into clear, practical figures |
| Test your future lifestyle | Live for three months on your projected pension and save the difference | Identifies genuine sacrifices and adjustments before they become permanent |
| Act on the major levers | Housing, a car and debt matter more than small daily cuts | Brings you closer to your ideal pension with fewer frustrations |
FAQ:
Question 1
Is there a universal “ideal” pension amount for someone living alone?
Not really. There are broad ranges: many single people feel comfortable on between 1,800 and 2,200 per month in a city, and somewhat less in lower-cost areas. Your own ideal depends on rent, health and the lifestyle you want.Question 2
How early should I start calculating my solo retirement budget?
Start once you begin thinking seriously about retirement, often around 40–50. You can review and refine it every five years as your circumstances and prices change.Question 3
What if my projected pension is far below my “ideal” amount?
This is common. You can respond by reducing future fixed costs, saving and investing more, postponing retirement or planning a small side activity during early retirement.Question 4
Does owning my home change the ideal pension number?
Yes, significantly. Without rent, many single people can live comfortably on 1,400–1,800 per month, depending on where they live and their health costs. You will still need to budget for taxes, charges and maintenance.Question 5
How often should I revisit my retirement plan when I live alone?
Reviewing it every two or three years is a sensible rhythm. Prices change, while your health and preferences develop, and your “ideal” may change alongside them.
Comments
No comments yet. Be the first to comment!
Leave a Comment